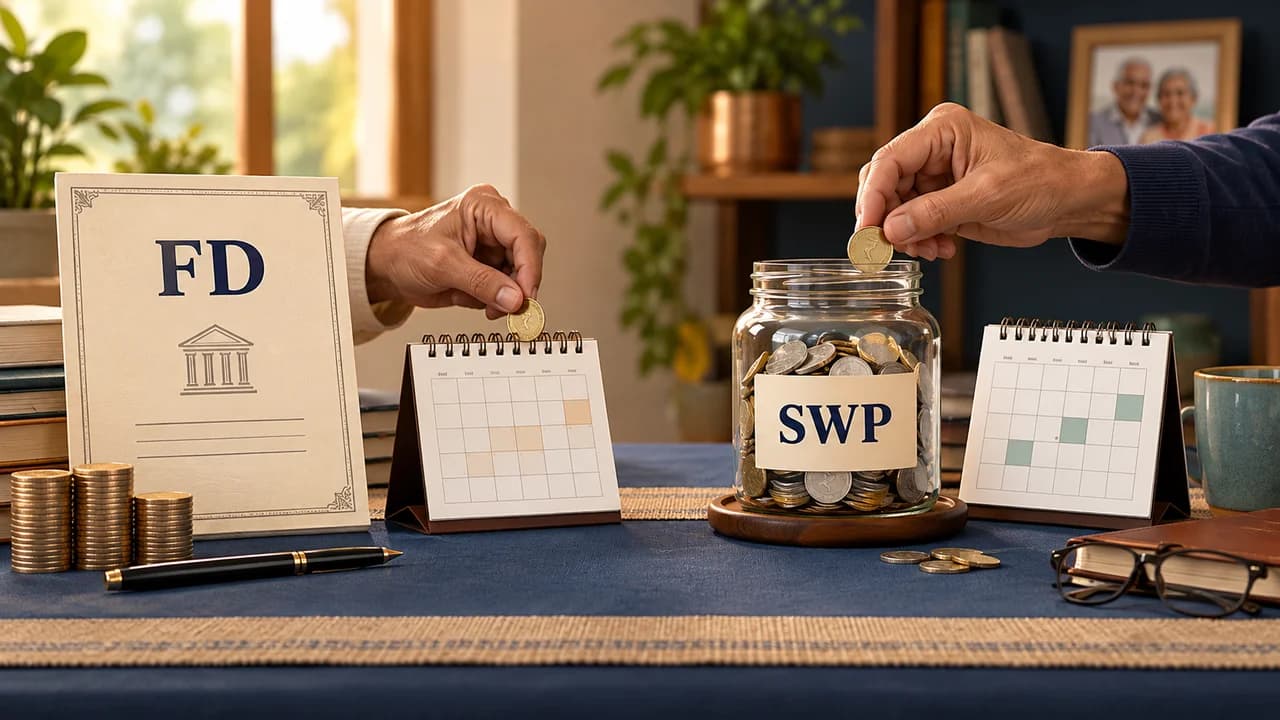
Two retirees withdraw ₹50,000 a month. One receives interest from a deposit. The other runs an SWP from a mutual fund. The bank credits look similar, but the money is being produced differently.
That difference affects both risk and tax.
What an FD pays
A fixed deposit pays contractual interest under its terms. Interest generally forms part of taxable income and is taxed at the applicable rate after considering the person's overall tax position.
A retiree does not automatically lose 30% of every rupee. Residence, total income, regime, deductions, rebates and special circumstances can change the calculation. TDS is a collection mechanism; it is not necessarily the final tax liability.
Deposits also have inflation risk, renewal-rate risk and concentration considerations. Premature withdrawal may reduce the applicable interest or trigger a contractual penalty. Compare the actual terms and applicable deposit-insurance protection.
What an SWP pays
An SWP instructs a mutual fund to redeem units periodically. The payout may include invested capital as well as gains. It is not a separate return product and does not guarantee a salary.
If ₹50,000 redeemed consists of ₹42,000 cost and ₹8,000 gain, the capital-gains computation generally focuses on ₹8,000, under the relevant tax rules. That can make the taxable portion look small initially. It does not mean the fund generated ₹50,000 of income that month.
If withdrawals exceed sustainable returns, units and corpus can run down.
Tax depends on the underlying fund
Eligible long-term equity-oriented gains have the aggregate ₹1.25 lakh annual threshold and applicable 12.5% base rate above it. Short-term equity gains and specified debt-fund gains have different treatment. Fund classification, lot dates and the relevant law must be checked.
The threshold is shared with other eligible equity long-term gains. It is not a fresh monthly allowance, and it cannot guarantee that an SWP above ₹1 lakh a month will always be tax-free. Tax planning should not lead a retiree into unsuitable equity exposure.
Model a bad first year
Suppose markets fall while monthly redemptions continue. More units may need to be sold to fund the same amount. A later recovery then works on fewer units. This sequence risk matters especially at the start of retirement.
Use realistic spending, inflation, tax and drawdown scenarios. Keep near-term needs appropriately funded and decide how discretionary withdrawals could change during weak markets.
Compare complete arrangements
A household may combine deposits and mutual-fund withdrawals instead of choosing one winner. Essential expenses, pension income, reserve needs and risk capacity should drive that allocation.
Choose the structure whose cash flow you understand and whose risks you can manage. A lower tax bill on an early redemption is useful, but it does not establish a safer retirement plan.
Frequently Asked Questions
Is every FD investor taxed at 30%?+
Can an SWP guarantee tax-free monthly income?+
Sources & References
- [1] Income Tax Department: tax rates and computationOfficialUsed for: Removed the universal 30% FD tax and ₹1 lakh tax-free monthly SWP promise; clarified income slabs, gain components and corpus depletion.Verified: 23 Oct 2026
- [2] SEBI: mutual fund master circular, 20 March 2026OfficialUsed for: Removed the universal 30% FD tax and ₹1 lakh tax-free monthly SWP promise; clarified income slabs, gain components and corpus depletion.Verified: 23 Oct 2026
Disclosure & Update History
This content is for educational purposes only and is not personalized financial, tax, or legal advice.
Update history
- Originally published on 23 March 2026.
- Updated 23 October 2026: Removed the universal 30% FD tax and ₹1 lakh tax-free monthly SWP promise; clarified income slabs, gain components and corpus depletion.
- Latest editorial review completed on 23 October 2026.
- Sources cited on this page are reviewed during each editorial refresh.
Tags
Written by Amodh Shetty
Amodh is a personal finance educator and the founder of KnowYourFinance. He focuses on Indian taxation, investing, insurance, and household decision-making frameworks.
Editorial disclosure: The author holds investments in broad-market index funds and SGBs. This article is strictly for educational purposes and does not constitute professional investment advice.
Need Calculators Alongside the Guide?
The article stands on its own. If you want an iPhone companion for running scenarios, saving inputs, and using India-focused calculators, you can use the KnowYourFinance app.
Explore the iPhone App