A joint account can make everyday banking easier. After one holder dies, the same account raises two questions: who can receive the money from the bank, and who ultimately owns it?
Answer them separately.
What the survivorship mandate does
An Either or Survivor instruction generally allows the bank to act on the survivor's claim after a holder dies, subject to identity, death evidence, the mandate, applicable directions and any restraining order or dispute affecting payment.
It is intended to simplify settlement. It does not mean the bank must instantly pay without checks, and it does not mean the account automatically freezes in every case. The earlier headline overstated that risk.
RBI's deceased-claims framework introduced standardised requirements with implementation by 31 March 2026. Ask the bank for its current documented process and the list appropriate to your account and claim.
Payment is not the final inheritance decision
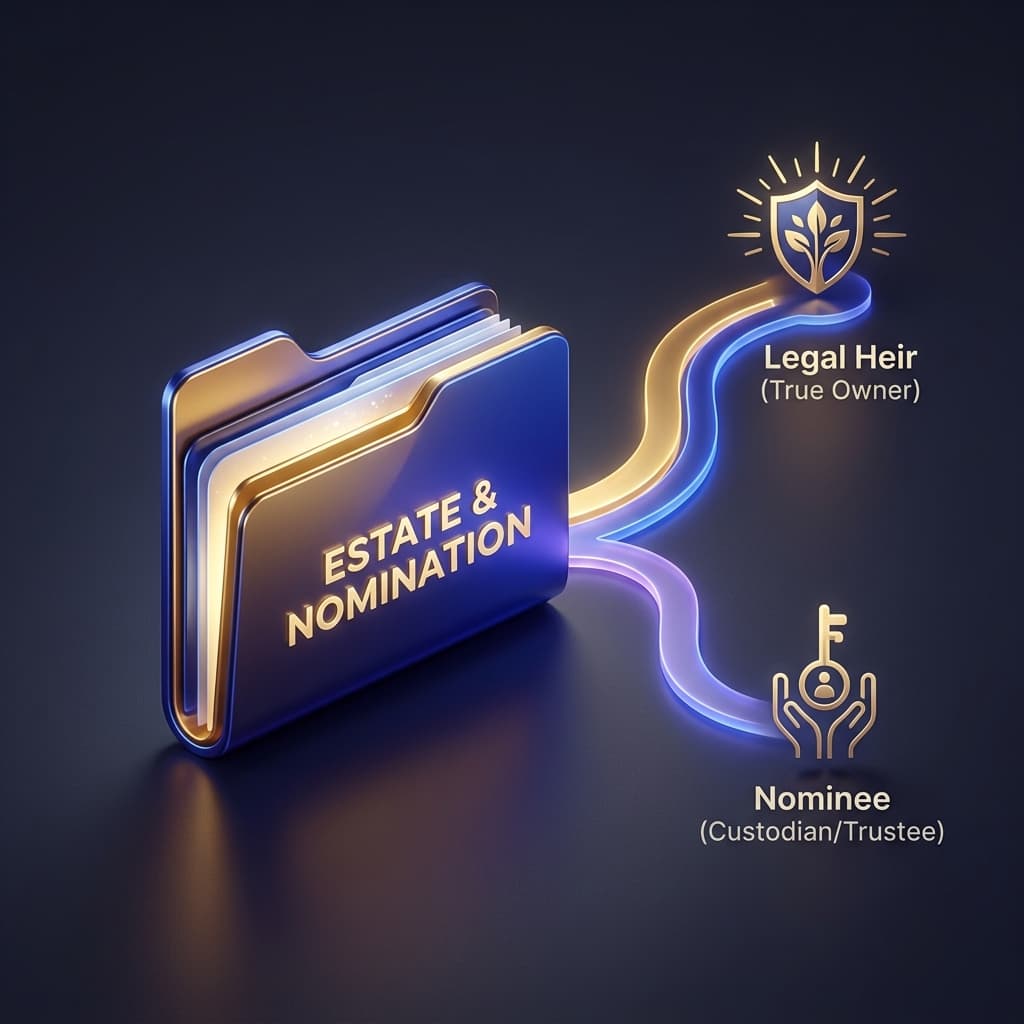
The bank's valid discharge does not necessarily settle competing beneficial ownership claims. The deceased holder's interest may form part of the estate under the applicable will and succession law.
Equally, it is wrong to say the entire account always belongs to the deceased's heirs. The survivor may have a beneficial share based on contributions, ownership and other evidence. The banking label alone does not answer every property-law question.
Keep records of significant contributions and the purpose of the joint holding, especially where ownership is unequal.
Nomination has a different role
A nomination helps identify a recipient under the relevant legal framework. It is not a universal override of inheritance rights. In a joint account, the stage at which a nomination operates must be checked; it should not be confused with the survivor mandate.
The combination of a nomination and a registered will cannot guarantee that probate, legal evidence or litigation will never be needed. Registration is also not what makes every valid will valid. Applicable law, execution and the family's facts matter.
Give the family usable records
Keep the account mandate, bank details, nominee record, contribution evidence and estate documents accessible to the appropriate family members. They should know how to notify the bank and obtain the current claim form.
If the money includes a business balance, unequal family contributions or contested ownership, get legal advice before distributing it. A withdrawal allowed by the bank is not permission to disregard another person's lawful entitlement.
The value of Either or Survivor is practical access. Pair that convenience with clear ownership and succession records rather than expecting one account instruction to do every job.
Frequently Asked Questions
Does an Either or Survivor account always freeze after one death?+
Does the deceased’s estate automatically own the entire joint balance?+
Sources & References
- [1] RBI: settlement of deceased customer claimsOfficialUsed for: Removed automatic freezing and universal succession-certificate claims; separated survivor access from inheritance and the deceased holder’s interest.Verified: 23 Oct 2026
- [2] Indian Succession ActOfficialUsed for: Removed automatic freezing and universal succession-certificate claims; separated survivor access from inheritance and the deceased holder’s interest.Verified: 23 Oct 2026
Disclosure & Update History
This content is for educational purposes only and is not personalized financial, tax, or legal advice.
Update history
- Originally published on 22 March 2026.
- Updated 23 October 2026: Removed automatic freezing and universal succession-certificate claims; separated survivor access from inheritance and the deceased holder’s interest.Compliance deadline: 31 March 2026.
- Latest editorial review completed on 23 October 2026.
- Sources cited on this page are reviewed during each editorial refresh.
Tags
Written by Amodh Shetty
Amodh is a personal finance educator and the founder of KnowYourFinance. He focuses on Indian taxation, investing, insurance, and household decision-making frameworks.
Editorial disclosure: The author holds investments in broad-market index funds and SGBs. This article is strictly for educational purposes and does not constitute professional investment advice.
Need Calculators Alongside the Guide?
The article stands on its own. If you want an iPhone companion for running scenarios, saving inputs, and using India-focused calculators, you can use the KnowYourFinance app.
Explore the iPhone App