A family knows there is a mutual-fund portfolio. The investor has died, and nobody knows which form to fill. At that point, a nomination is helpful—but it is not the whole inheritance plan.
What changed from September 2026
SEBI's 29 May 2026 circular took effect on 1 September 2026. It provides for nomination in newly opened single-holder accounts or folios unless the investor submits the prescribed opt-out. Nomination is optional for joint holdings, with joint-holder consent required for changes.
The current framework permits up to three nominees. It provides online and offline processes and requires acknowledgements. Check the actual recorded nomination rather than relying on an old form you intended to submit.
These are operational rules. They do not turn a nominee into the unquestioned beneficiary of every estate regardless of succession law.
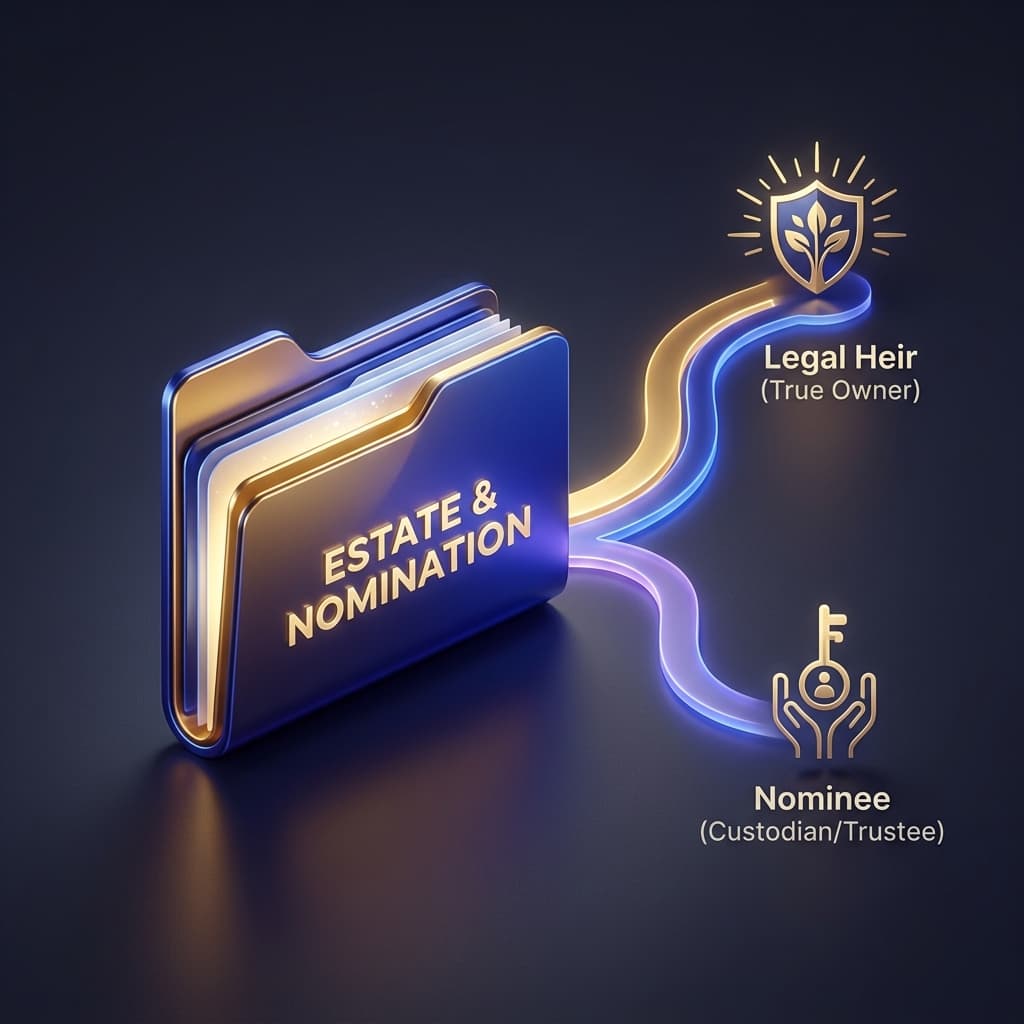
Access and inheritance are separate
A nominee helps the institution transmit the holding under the applicable framework. Ultimate rights can still be governed by a valid will and succession law. Do not import the special beneficial-nominee rules for some life-insurance cases into mutual funds automatically.
A valid will does not universally require registration. Execution, applicable law and any probate requirement matter. Calling only a registered will valid, as the previous article did, was incorrect.
August 2026: the transmission framework also changed
First establish who died and how the units are held. Surviving joint holders, a sole holder with a nominee, legal heirs without nomination and HUF cases have different document paths. Demat holdings also involve the depository participant's process.
SEBI's circular dated 23 July 2026 introduced a standardised transmission framework, commencing 30 days after issue. It includes model forms, a low-value Quick Transmission Processing route and revised simplified-documentation thresholds. The simplified threshold is ₹10 lakh for the specified physical/SOA per-AMC setting and ₹30 lakh for the specified demat setting; valuation and aggregation conditions still matter.
Use its current annexures and the processing entity's implemented forms. Older AMFI T1/T2/T3 labels should not be treated as the only current filing instruction. The circular also removes a mandatory-probate requirement within the revised operational framework. This does not resolve a contested inheritance claim or remove the need for applicable ownership evidence.
Do not use one amount as a universal legal rule
Documentation depends on claim type, holding mode, value, available evidence and whether the claim is disputed. An earlier statement that every holding above ₹5 lakh without nomination requires probate or a succession certificate was too broad.
Use the current matrix for the exact case. Death evidence, claimant KYC and bank details, signatures, indemnity, consent or legal title documents may be relevant. Where family members disagree, simplified operational paperwork does not settle the underlying dispute.
Make the records useful while you can
Keep a folio and demat list, current nominee acknowledgements and estate documents accessible to the appropriate family members. Review them after marriage, a birth, death or change in intended beneficiaries.
Good records reduce avoidable delay. They work best when the nomination, ownership and estate plan tell a consistent story.
Frequently Asked Questions
Must every valid will be registered?+
Which transmission form should a nominee use?+
Sources & References
- [1] SEBI: modified nomination norms, 29 May 2026OfficialUsed for: Added SEBI nomination norms effective 1 September 2026; corrected T2/T3 mapping, registered-will requirement and universal ₹5 lakh court-certificate rule.Verified: 23 Oct 2026
- [2] Indian Succession ActOfficialUsed for: Added SEBI nomination norms effective 1 September 2026; corrected T2/T3 mapping, registered-will requirement and universal ₹5 lakh court-certificate rule.Verified: 23 Oct 2026
- [3] SEBI: standardised transmission framework, 23 July 2026OfficialUsed for: Current forms, commencement and simplified-documentation thresholdsVerified: 23 Oct 2026
Disclosure & Update History
This content is for educational purposes only and is not personalized financial, tax, or legal advice.
Update history
- Originally published on 11 June 2026.
- Updated 23 October 2026: Added September nomination norms and the July transmission framework effective 30 days after issue; corrected old form mapping, registered-will and universal probate claims.Rules effective: 1 September 2026.
- Latest editorial review completed on 23 October 2026.
- Sources cited on this page are reviewed during each editorial refresh.
Tags
Written by Amodh Shetty
Amodh is a personal finance educator and the founder of KnowYourFinance. He focuses on Indian taxation, investing, insurance, and household decision-making frameworks.
Editorial disclosure: The author holds investments in broad-market index funds and SGBs. This article is strictly for educational purposes and does not constitute professional investment advice.
Need Calculators Alongside the Guide?
The article stands on its own. If you want an iPhone companion for running scenarios, saving inputs, and using India-focused calculators, you can use the KnowYourFinance app.
Explore the iPhone App