You can spend weeks comparing funds and still end up with ten versions of the same exposure. A simpler portfolio can be easier to understand and maintain.
But 'only three funds' should be a starting conversation, not a law.
Give each holding a job
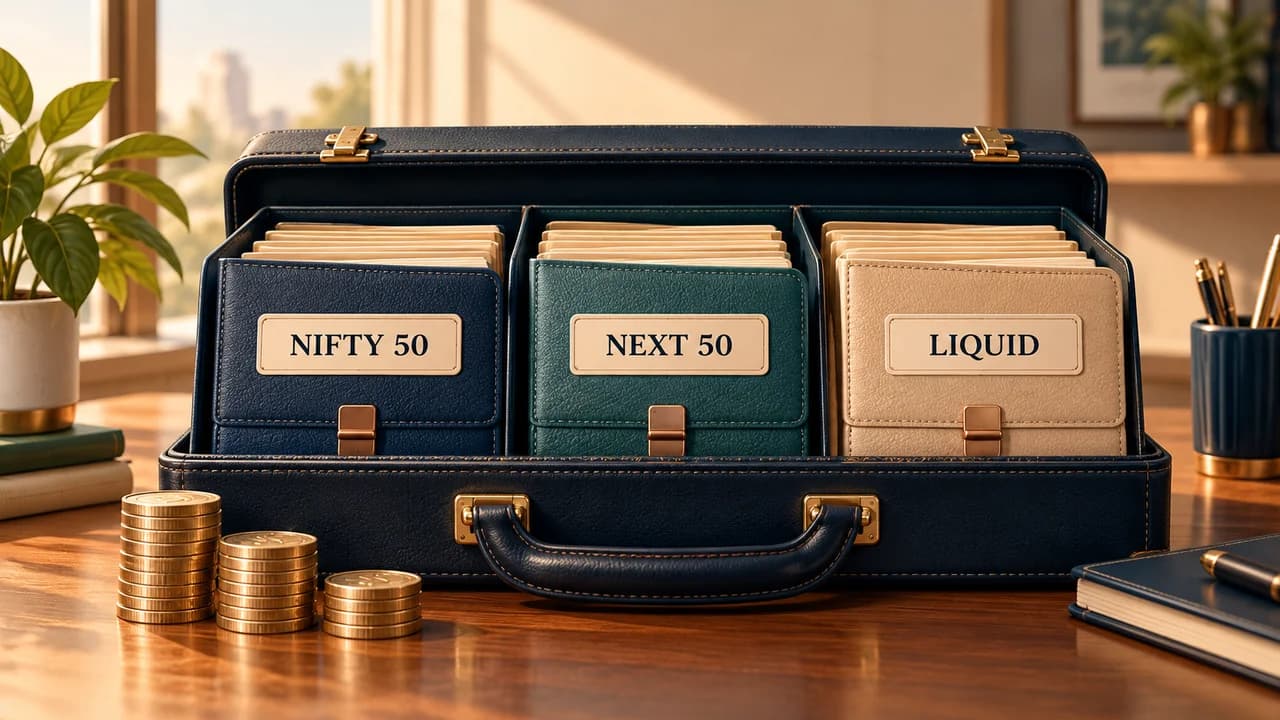
One possible structure combines a core equity exposure, an additional equity allocation and a short-term debt bucket. Nifty 50, Nifty Next 50 and a liquid fund can illustrate those roles, but they are not a complete recommendation for every reader.
Nifty Next 50 is not merely a safer extension of Nifty 50. Its composition and risk can differ materially, and it can be volatile. Together the indices cover their defined company universe, not the whole Indian market or international assets.
A liquid fund invests in short-maturity instruments under its mandate. It still has investment, liquidity and operational risks and is not an insured savings account.
Decide allocation before count
A person needing money next year should not adopt the same equity mix as someone saving for retirement in twenty years. Emergency reserves, debts, insurance and existing EPF or PPF holdings also affect the plan.
Write down the goal, horizon and intended equity/debt allocation first. Then ask how few products can implement it reliably.
Compare costs correctly
A portfolio holding three funds does not automatically pay three expense ratios on every rupee. The portfolio expense is weighted by the allocation to each fund. Additional funds may add fees or complexity, but count alone does not establish the cost.
For index funds compare tracking difference, expenses, operational reliability and how closely the product follows its stated benchmark. Passive investing reduces some manager-selection decisions; it does not create zero manager or operational risk.
Check overlap and category fit
Use actual underlying holdings to assess duplication. Two funds can be distinct enough to serve different roles, while eight names may still concentrate in similar companies.
SEBI's February 2026 categorisation framework is another reason to read the current scheme mandate rather than relying only on the product label or an old comparison.
Keep the plan maintainable
Choose a review frequency and a rebalancing rule you can follow without constantly switching funds. Consider exit loads and tax before replacing an existing holding.
The benefit of simplicity is behavioural and operational: you can explain what you own and why. It does not guarantee outperformance or establish that a fourth fund is automatically a mistake.
Frequently Asked Questions
Are exactly three funds enough for everyone?+
Do more funds automatically multiply fees on the whole portfolio?+
Sources & References
- [1] SEBI: mutual fund master circular, 20 March 2026OfficialUsed for: Removed guaranteed superiority, stacked-fee arithmetic and zero-manager-risk claims; clarified Nifty Next 50 concentration and liquid-fund risk.Verified: 23 Oct 2026
- [2] SEBI: scheme categorisation, 26 February 2026OfficialUsed for: Removed guaranteed superiority, stacked-fee arithmetic and zero-manager-risk claims; clarified Nifty Next 50 concentration and liquid-fund risk.Verified: 23 Oct 2026
Disclosure & Update History
This content is for educational purposes only and is not personalized financial, tax, or legal advice.
Update history
- Originally published on 24 February 2026.
- Updated 23 October 2026: Removed guaranteed superiority, stacked-fee arithmetic and zero-manager-risk claims; clarified Nifty Next 50 concentration and liquid-fund risk.
- Latest editorial review completed on 23 October 2026.
- Sources cited on this page are reviewed during each editorial refresh.
Tags
Written by Amodh Shetty
Amodh is a personal finance educator and the founder of KnowYourFinance. He focuses on Indian taxation, investing, insurance, and household decision-making frameworks.
Editorial disclosure: The author holds investments in broad-market index funds and SGBs. This article is strictly for educational purposes and does not constitute professional investment advice.
Need Calculators Alongside the Guide?
The article stands on its own. If you want an iPhone companion for running scenarios, saving inputs, and using India-focused calculators, you can use the KnowYourFinance app.
Explore the iPhone App