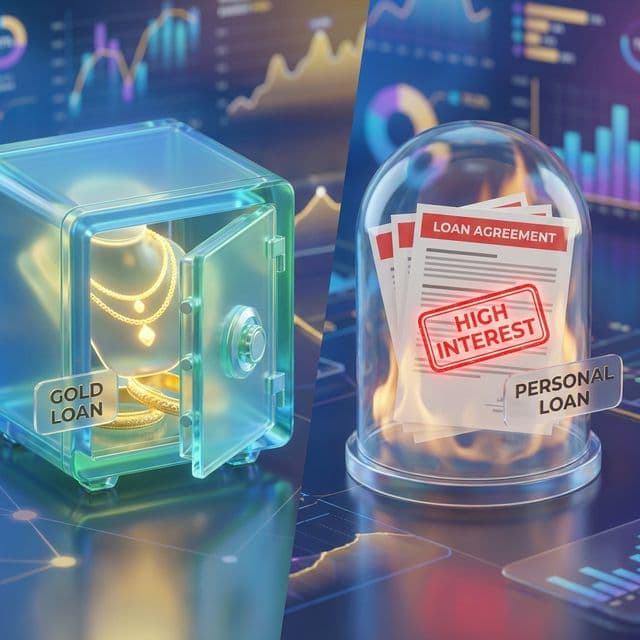
A personal loan threatens your monthly cash flow. A gold loan puts something tangible on the line. That does not make either one automatically safer.
Start with how you will repay, then compare the total cost.
What the gold-loan limits actually say
RBI's gold-and-silver collateral directions required compliance by 1 April 2026, with transitional treatment for relevant existing loans. For covered consumption loans against eligible collateral, the maximum LTV depends on the loan size: 85% up to ₹2.5 lakh, 80% above ₹2.5 lakh and up to ₹5 lakh, and 75% above ₹5 lakh.
These are ceilings, not a promise that every applicant will receive that amount. Lenders may lend less. Valuation considers eligible metal content; do not treat stones, workmanship or your jewellery invoice as fully financeable value. The applicable LTV must be maintained during the loan, and bullet-repayment calculations have their own requirements.
The old statement that RBI caps every gold loan at 75% is therefore incomplete.
Collateral does not remove risk
A lender still faces price, valuation, operational and repayment risks. The borrower risks losing pledged items through the contractual recovery process. A fall in gold prices can also affect the collateral cushion.
Do not pledge sentimental jewellery unless you understand the auction notice process and can live with the consequences of non-payment. Ask about custody, insurance, release timelines and charges before handing it over.
Compare like-for-like costs
Obtain a current quotation for the same amount and repayment period. Compare APR, processing and valuation charges, any renewal cost, applicable taxes and the repayment schedule.
An EMI loan steadily reduces principal. A bullet structure may leave a substantial payment due at maturity. A lower advertised annual rate does not solve the problem if you cannot make the final payment.
There is no universal current 8.5% gold rate or 14–18% personal-loan rate. Lender, borrower profile and product terms change the quote.
Credit reporting still matters
A secured loan is not invisible to credit bureaus. Late repayment or default can hurt your record. Do not assume a gold loan has a special exemption from the consequences that apply to other reported borrowing.
A personal loan avoids pledging gold, but its pricing and affordability still need checking. Compare both with other realistic options, including reducing the amount borrowed or using an existing emergency reserve.
Make the exit plan first
Write down the exact monthly payment or maturity amount and where it will come from. Stress-test a delayed salary or lower business income. Then ask how much interest and fees you would pay if you repaid early.
The better loan is the one that solves the immediate need with a repayment plan you can sustain. Collateral and a low headline rate are only parts of that decision.
Frequently Asked Questions
Is the maximum gold-loan LTV always 75%?+
Can a gold loan affect my credit record?+
Sources & References
- [1] RBI: gold and silver collateral directionsOfficialUsed for: Replaced the obsolete universal 75% LTV claim and false zero-risk and credit-score assurances.Verified: 23 Oct 2026
Disclosure & Update History
This content is for educational purposes only and is not personalized financial, tax, or legal advice.
Update history
- Originally published on 9 February 2026.
- Updated 23 October 2026: Replaced the obsolete universal 75% LTV claim and false zero-risk and credit-score assurances.Rules effective: 1 April 2026.
- Latest editorial review completed on 23 October 2026.
- Sources cited on this page are reviewed during each editorial refresh.
Tags
Written by Amodh Shetty
Amodh is a personal finance educator and the founder of KnowYourFinance. He focuses on Indian taxation, investing, insurance, and household decision-making frameworks.
Editorial disclosure: The author holds investments in broad-market index funds and SGBs. This article is strictly for educational purposes and does not constitute professional investment advice.
Need Calculators Alongside the Guide?
The article stands on its own. If you want an iPhone companion for running scenarios, saving inputs, and using India-focused calculators, you can use the KnowYourFinance app.
Explore the iPhone App