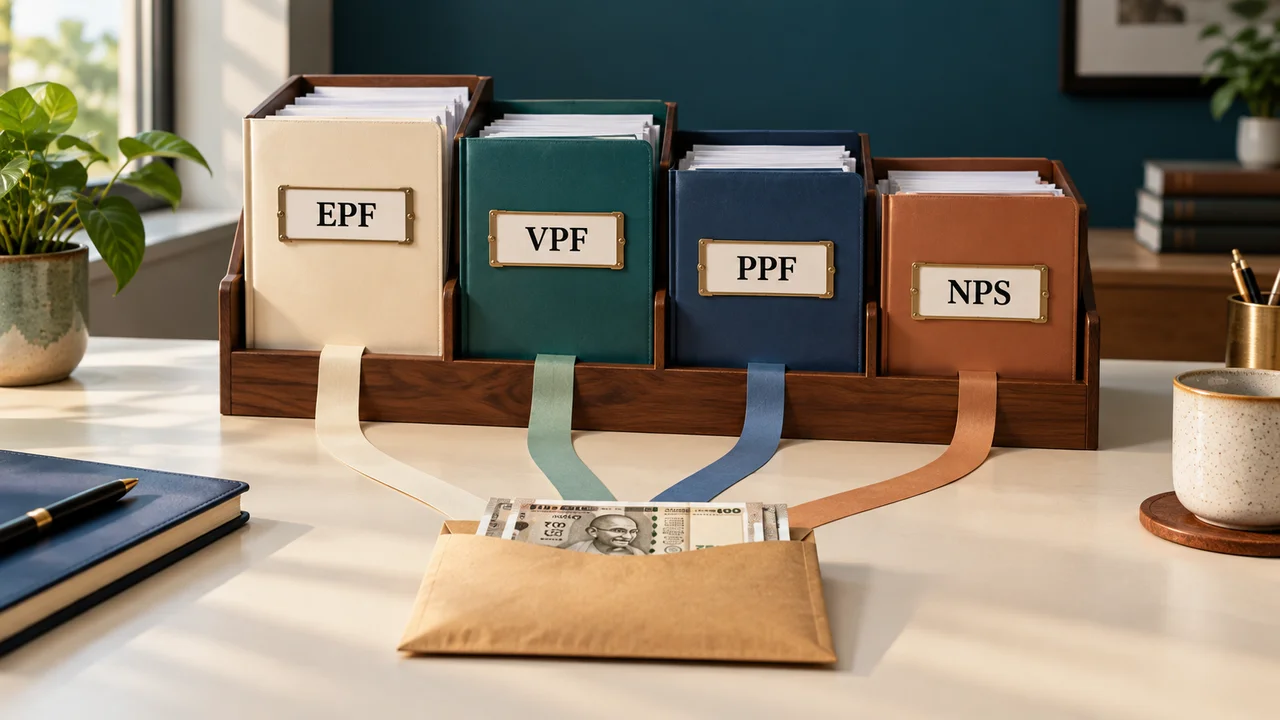
The question sounds reasonable: which should I fill first—VPF, PPF or NPS?
There is no useful answer until we know what is already in your portfolio and when you will need the money. A higher quoted rate does not make an account suitable for every goal.
Start with money you may need soon
Keep an emergency reserve and near-term commitments in accessible places. A retirement account should not become the source you depend on for next month's rent or a planned purchase.
Then list your required EPF contributions, employer benefits, existing long-term debt assets and equity exposure. This prevents an extra contribution from creating an accidental concentration.
EPF and VPF: linked to eligible employment
EPF is part of covered employment, with employee and employer allocations governed by the rules. VPF is a voluntary addition by the employee; the employer does not have to match the extra amount.
The declared EPF rate applies to a particular year. Do not project 8.25%, or any other quoted rate, as an unchanged lifelong offer. Interest attributable to employee contributions above the applicable threshold can be taxable. The usual threshold is ₹2.5 lakh where the employer also contributes, with a different ₹5 lakh threshold in qualifying cases without employer contributions.
Withdrawal exemptions and access rules have their own conditions. 'EPF is always tax-free and fully liquid after resignation' is not a sound planning assumption.
PPF: a different form of long-term debt saving
PPF has government backing, a 15-year original term, contribution limits and controlled access. Its rate is reviewed periodically. You do not lock today's rate for the full term.
It can fit an eligible self-employed investor or an employee who wants to diversify long-term savings. It is not merely a product to consider only after maximising VPF. Compare the additional contribution's tax treatment and access rules first.
NPS: choose an allocation, not just a deduction
NPS is market-linked and can hold equity and debt. Its usefulness does not end at the familiar additional personal deduction. Employer contributions can also change the comparison, subject to tax-regime and statutory limits.
The consolidated PFRDA exit rules through 20 July 2026 distinguish government and non-government subscribers. The general qualifying non-government normal-exit annuity minimum is 20%, while government normal exits generally retain 40%, subject to corpus and other exceptions. Premature exits differ.
An amount permitted to be withdrawn is not automatically tax-exempt. Check the separate income-tax rule before calculating retirement spending money. Do not treat the higher permitted non-annuity portion as an automatic matching increase in tax exemption.
Build your own order
For each extra rupee, ask:
- •Is the emergency reserve adequate?
- •Does the money need to remain accessible?
- •Is the portfolio short of debt stability or long-term growth exposure?
- •Does this contribution actually qualify for a tax benefit under my chosen regime?
- •What happens when I change jobs or retire?
For one household, extra VPF may fit well. For another, PPF or an NPS allocation may be more useful. A third may need to keep the money liquid rather than add another locked retirement contribution.
The best priority order follows the household's needs. It should not be copied from a single interest-rate ranking.
Frequently Asked Questions
Should VPF always come before PPF?+
Should I use NPS only to claim the extra personal deduction?+
Sources & References
- [1] PFRDA exit regulations, consolidated through 20 July 2026OfficialUsed for: Removed the fixed product hierarchy, unconditional EPF tax-free claim and NPS-only-for-deduction recommendation; incorporated current NPS exit distinctions.Verified: 23 Oct 2026
- [2] Income Tax Department: tax rates and computationOfficialUsed for: Removed the fixed product hierarchy, unconditional EPF tax-free claim and NPS-only-for-deduction recommendation; incorporated current NPS exit distinctions.Verified: 23 Oct 2026
- [3] EPFO member FAQsOfficialUsed for: Removed the fixed product hierarchy, unconditional EPF tax-free claim and NPS-only-for-deduction recommendation; incorporated current NPS exit distinctions.Verified: 23 Oct 2026
- [4] National Savings InstituteOfficialUsed for: Removed the fixed product hierarchy, unconditional EPF tax-free claim and NPS-only-for-deduction recommendation; incorporated current NPS exit distinctions.Verified: 23 Oct 2026
Disclosure & Update History
This content is for educational purposes only and is not personalized financial, tax, or legal advice.
Update history
- Originally published on 23 February 2026.
- Updated 23 October 2026: Removed the fixed product hierarchy, unconditional EPF tax-free claim and NPS-only-for-deduction recommendation; incorporated current NPS exit distinctions.Consolidated source date: 20 July 2026.
- Latest editorial review completed on 23 October 2026.
- Sources cited on this page are reviewed during each editorial refresh.
Tags
Written by Amodh Shetty
Amodh is a personal finance educator and the founder of KnowYourFinance. He focuses on Indian taxation, investing, insurance, and household decision-making frameworks.
Editorial disclosure: The author holds investments in broad-market index funds and SGBs. This article is strictly for educational purposes and does not constitute professional investment advice.
Need Calculators Alongside the Guide?
The article stands on its own. If you want an iPhone companion for running scenarios, saving inputs, and using India-focused calculators, you can use the KnowYourFinance app.
Explore the iPhone App